Showing posts with label ventana gold. Show all posts

Thursday, January 27, 2011

Ventana Gold (VEN.to): Eike winning

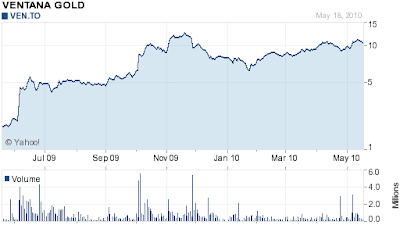
Despite Ventana Gold's (VEN.to) head honcho Stephen Orr jawboning it to Reuters yesterday and talking about the "some different interest" from as yet mysterious third parties and the "value that (the stock) would be able to gain over the next 12 to 18 months" if VEN were left to get on with things, we return to the eternal baseline of MoneyTalksBullshitWalks and the VEN.to price chart below, which includes the share price action since Eike's Nov 17th offer and the price ($12.63) the Brazilian dude is willing to pay via the red line:


For the first time since then, VEN.to closed today under the offer price (a penny to be exact, at $12.62). With the Feb 14th offer deadline now looming closer, this war of attrition is starting to sway the way of the Latino team. Tudo bem.

Disclosure: No position, cos The IKN Weekly took the $13.51 profits in November. So there.

Wednesday, November 17, 2010

Ventana Gold (VEN.to): What does the Can of Corn say?


The Can of Corn says: "TOO LOW, EIKE!"

Nicholas CampbellSoup has just raised his target from $14.75 to $15.50, saying that this bid needs to sweeten or face a counter. Read the Can of Corn PDF right here, hot off the presses.

(You got 11 minutes left in the trading day, dudettes and dudes: 3:49pm local time here.)

PS: By the way, this is part of a Flash update sent to subscribers less than 10 minutes after the opening bell this morning:
"...However, the advice is to hold your shares of VEN.to and do not sell them today, as the market seems to be pricing in a pot-sweetener right now and there's every chance that the final deal will go through at a higher price than today's offer. We'll keep a close eye on proceedings and if our "hold your shares" call changes you'll be notified immediately...."
 Just sayin'

Ventana Gold (VEN.to): Eike makes his move

MM, you owe me a beer my friend!


Here's the link, here's the story:

TORONTO, Nov. 17 /CNW/ - EBX today announced its intention to make an all-cash offer to acquire all of the issued and outstanding common shares of Ventana Gold Corp. ("Ventana") (TSX:VEN) that it does not own at a price of C$12.63 in cash per Ventana common share (the "Offer").
63X Master Fund, a company indirectly controlled by Eike F. Batista, beneficially owns approximately 20,806,000 common shares of Ventana (including common shares underlying outstanding special warrants owned by 63X Master Fund), representing approximately 20% of Ventana's outstanding common shares (on a fully diluted basis).
The Offer values the total equity of Ventana at approximately C$1.5 billion on a fully diluted basis.
The Offer represents an attractive premium of 26 per cent to the closing price of Ventana's common shares on the Toronto Stock Exchange ("TSX") on November 16, 2010. It is also a premium of 30 per cent to the volume weighted average trading price of Ventana's common shares on the TSX for the 30-day trading day period ended on the same date. The Offer will be fully funded and provides Ventana's shareholders with immediate liquidity and certainty of value regarding Ventana's growth potential in the face of volatile equity markets.
About the Offer
EBX plans to formally commence its Offer as soon as practicable. The Offer will be open for acceptance for not less than35 days from the date of its commencement.
The Offer will be subject to continues here

Monday, November 8, 2010

Ventana Gold (VEN.to) upped to spec buy at TD Sec

Wanna know what Daniel Earle thinks about today's Ventana Gold (VEN.to) news? Click this link and download your own copy of his analysis, but here's the headline blurb that comes with it.

Ventana released the much anticipated results of the Scoping Study and resource estimate for its wholly-owned La Bodega gold project in northern Colombia this morning.
Scoping Study highlights:
 
-Initial inferred resource of 3.5mm oz Au (range of 3mm oz to 6.7mm oz depending on cut-off selected), 19mm oz Ag, 85mm lbs Cu
-Start-up capital costs of US$297mm (incremental US$169mm over LOM)
-14 year mine life with planned production at 7500 tpd
-Average production of 301,000 oz/yr Au at net cash costs of US$322/oz over first 6 years
-Reported pre-tax NAV5% of US$807mm with IRR of 34% at metal prices of US$1000/oz Au , US $17/oz Ag, and US$3.00/lb Cu
 
It is difficult to gauge Street expectations as the company has a limited following. However, the figures presented above taken together are broadly inline with our expectations, with the project being smaller at this time but also more profitable than we had anticipated.
 
We believe this sets a baseline upon which the company can expand and improve the project. Moreover, we believe this milestone may mark the emergence of the company from a long period of underperformance typical of companies during the feasibility stage of their life cycle.

As such, we are upgrading the stock to Speculative BUY (from Hold) and increasing our Target Price to $16/share (from $14).

IKN back. Earle was early and good on the VEN story in '09 but just recently has been fiddling around with his call and got a bit too cute for his own good by downgrading to hold just a couple of weeks ago. Nice to see he's back with the right call on VEN now. DYODD, dude.

Friday, September 3, 2010

When Argentina suddenly becomes the fashion place for risk capital......

....you just know it's going to all end in tears.

But no matter in the very short term, as today's news about Andean Resources (AND.to) (AND.ax) and Goldcorp (GG) has set off a mini-bullrun in juniors exposed to the land of the Kirchners. For example the Argy silver play Mirasol (MRZ.v)....

...and much to my pleasant surprise (cos I didn't sell 'em yesterday) Minera Andes (MAI.to):

Meanwhile, wiser souls are indeed looking a little further afield for the next big gold deposit to get sold. Example Ventana Gold (VEN.to):

Others too. DYODD

Thursday, July 29, 2010

Ventana Gold (VEN.to): A window (geddit?) on a niche market


So this morning Ventana Gold (VEN.to) released this news which told the world that the land purchase deal was done and dusted. The reaction to that can be seen in the above five day chart....yeah, the market liked it.

But what gets me is that anyone with an inkling knew that there wouldn't be any last minute hitches on this deal and it was a lock to go through as intended. So on seeing this reaction today, my thoughts turn to the general nervousness of the markets and how it likes to see solid, done deals at a time like this instead of verbal agreements. But it also turns to the continuing outright ignorance that the money community has of the LatAm culture and mindset, because as soon as the Gelvez clan had come to agreed terms with VEN.to there was no way they'd renege on the deal...no way at all....ask any latino.

There must be a way to make a profit from this lack of LatAm nous that's patently displayed time and again by people with more money than LatAm sense. Now if only there were a blog out there that concentrated on LatAm junior mining and its way of life........

Tuesday, June 8, 2010

Beaty sells Ventana (VEN.to)

He bought 'em at two, he sells 'em at ten. Ross cashes in on VEN.

Ventana Gold Corp. (VEN)

As of June 7th, 2010
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
Jun 07/10 Jun 01/10 Lumina Capital Limited Partnership Direct Ownership Common Shares 10 - Disposition in the public market -97,400 $10.104
Jun 07/10 May 31/10 Lumina Capital Limited Partnership Direct Ownership Common Shares 10 - Disposition in the public market -254,400 $10.245
Jun 07/10 May 28/10 Lumina Capital Limited Partnership Direct Ownership Common Shares 10 - Disposition in the public market -130,700 $10.311
Jun 07/10 May 27/10 Lumina Capital Limited Partnership Direct Ownership Common Shares 10 - Disposition in the public market -400,000 $10.564
Jun 07/10 May 26/10 Lumina Capital Limited Partnership Direct Ownership Common Shares 10 - Disposition in the public market -1,247,700 $10.606


Eike bought half.

Monday, May 31, 2010

we lead others follow

Let's see if you can spot the similarities too, dear reader.

Here's IKN on Friday May 28th:
How many Ventana Gold (VEN.to) shares does Eike Batista Own?

Answer: 19,306,000.


This number went up this week, as Eike's 63X Master Fund vehicle added 1.1m shares to its pile on Wednesday (and filed them as quickly as yesterday).


Ventana Gold Corp. (VEN)

As of May 27th, 2010
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
May 27/10 May 26/10 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 1,100,000 $10.620


Strangely and weirdly, this puts the 63X Master Fund's total holding at 19.82% of shares outstanding, assuming that the May 13th total of 97,409,131 shares out is still the exact correct one. As many out there will know, special things start happening to Canadian stocks if one single holder goes above 20% so it's not really surprising to see Eike's crew stop just under that magic number.

Now that the land deal is done with Los Gelvez, the question now is "when" Eike makes his move and buys out VEN.to, not "if". My best guess would be after the Presidential elections, but WTFDIK? Anyway, to round off here's the current state of full dilution at the company (the warrants and options are all in the money). I wonder if mgmt will have time to squeeze in a final round of bonus options?

shares out: 97,409,131
warrants: 3,644,000
options: 6,327,000


And now here's the Ventana Gold (VEN.to) news release on Monday May 31st:

VANCOUVER, BRITISH COLUMBIA--(Marketwire - 05/31/10) - Ventana Gold Corp. (TSX:VEN - News) ("Ventana" or "the Company") is pleased to announce that 63X Master Fund ("63X"), its largest shareholder, has acquired ownership and control of an additional 1.1 million common shares of Ventana through the facilities of the Toronto Stock Exchange, bringing its aggregate ownership in Ventana to 19,306,000 common shares. 63X paid cash consideration of $10.62 per share, for aggregate consideration of $11,682,000.

Ventana Chairman Richard Warke said: "We are pleased to see 63X increase its position in our company. This demonstrates their confidence in the value of our assets and the strength of our business plan. As our largest shareholder, they have shown tremendous support to our Board and management team."

Friday, May 28, 2010

How many Ventana Gold (VEN.to) shares does Eike Batista own?


Answer: 19,306,000.

This number went up this week, as Eike's 63X Master Fund vehicle added 1.1m shares to its pile on Wednesday (and filed them as quickly as yesterday).

Ventana Gold Corp. (VEN)

As of May 27th, 2010
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
May 27/10 May 26/10 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 1,100,000 $10.620


Strangely and weirdly, this puts the 62X Master Fund's total holding at 19.82% of shares outstanding, assuming that the May 13th total of 97,409,131 shares out is still the exact correct one. As many out there will know, special things start happening to Canadian stocks if one single holder goes above 20% so it's not really surprising to see Eike's crew stop just under that magic number.

Now that the land deal is done with Los Gelvez, the question now is "when" Eike makes his move and buys out VEN.to, not "if". My best guess would be after the Presidential elections, but WTFDIK? Anyway, to round off here's the current state of full dilution at the company (the warrants and options are all in the money). I wonder if mgmt will have time to squeeze in a final round of bonus options?

shares out: 97,409,131
warrants: 3,644,000
options: 6,327,000

Friday, May 7, 2010

Ventana Gold (VEN.to), reader feedback and the difference between what goes on here at the blog and what goes on in The IKN Weekly

This morning I received one of the nicest mails ever from a long-time reader and subscriber to The IKN Weekly. The dude in question has been a fan of and investor in Ventana Gold (VEN.to) for a long time and we've swapped ideas on the stock on more than one occasion, but today he told me something I hadn't known. When the Ventana property problems hit back in November, your author ran an analysis of the situation in IKN31 and offered some practical advice. It turns out that 'Subscriber X' (as we'll call him) took that advice and, without ever mentioning it, sold the majority of his VEN stock. He then went about repurchasing at much lower prices earlier in 2010 and has made a big difference to an already winning position. I've been given permission to excerpt from his mail (and excuse the missing bits, but there's some sensitive information edited out by necessity):

"....a key factor in my Ventana trade was your analysis in that edition (ottonote: IKN31). General market consensus at the time was resolution would occur in days or weeks. You saw it differently, presented a solid case and I ran with that call. I sold .......... and then bought back (a couple of months later).........when prices were at lows. The insight you offered (in IKN31) made me a lot of money. Can I pay in advance for the next ten years?!".

(answer: no you can't :-).
As I say, that sell-buy move by Subscriber X was unknown to me until today. The dude (and believe me, he really is a 'dude') deserves full credit on the deal too, as it was all off his own bat. As for the advice proferred in IKN31, here how the discussion in the issue concluded, as it fairly sums up the position taken at that time:
"If I had to guess, I’d say that the most likely outcome is an equitable settlement that takes months. Not weeks and not years, but maybe 6 to 12 months. But that’s just my wild guesstimate and I’d need a lot more on-the-ground information before making anything more than a simple finger-in-the-air guess. But I will say that VEN will have to cut a deal with the locals at some point or other. Not much doubt about that one.

........

"By way of disclosure, I am not long or short VEN and intend to stay that way. With that said, my best guess is that the stock has further to drop before we get resolution on this matter. DYODD."
In the end, the deal didn't quite take six months, as start-to-finish of the problem turned out to be 5 1/2 months. But hey, the IKN analysis (based on facts and opinion extensively explained in that issue) was much closer than the talking heads back in November and December who were assuring the market that it would take just a couple of weeks to resolve, that any price under $10 should be snapped up and only a fool would sell this news. We were also right about a deal being cut and that the arbitration moves wouldn't amount to much and wouldn't bring about a final result (yet again, against the grain of popular opinion at the time).

The greatest thing about Subscriber X's long mail, the thing that gives me the greatest pleasure about it, was that he was smart enough to take the information offered up by The IKN Weekly and use it in his own way. In other words, a shining example of the best type of subscriber possible. Readers and subscribers know that this humble scribe has no direct exposure to Colombian junior mining through personal choice, but that doesn't stop us from analyzing the country and its development in an ongoing and level-headed way over at The IKN Weekly. This is one of the main differences between the ranty blog and the more measured tone of the Weekly (something that subbers tell me should change on the blog, but i don't care so much). The IKN Weekly doesn't treat people like sheep, telling them what they should or shouldn't do at any given moment; we try our best to offer up the facts before personal opinion and allow people to use the insight to form their own opinions.

Ventana Gold (VEN.to) halted


Ventana (VEN.to) got halted pending news just before the bell this morning. Has Eike done his deal with Gelvez? We'll probably add an update to this post later today. Only time will tell......

UPDATE: Yes indeed, VEN has nailed down its deal, but at what cost? Well, the original final payment was supposed to be $3m and 250,000 shares. Now it's a cool $48m. So well done to the Gelvez dude, his extorsion methods succeeded.

Friday, April 9, 2010

The inside track

Back with another one of our occasional looks at insider trades, with two today worthy of comment. Firstly, we note that Eike Batista is buying small ($1.5m or so is small for him) lumps of Ventana Gold (VEN.to) and topping up his large position on the open market:

Ventana Gold Corp. (VEN)

As of April 8th, 2010
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
Apr 08/10 Apr 05/10 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 75,200 $10.208
Apr 08/10 Apr 01/10 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 79,000 $9.676

That smacks of confidence.


On the flipside, what are the people running Baja Mining (BAJ.to) trying to tell us?

Baja Mining Corp. (BAJ)

As of April 8th, 2010
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
Apr 08/10 Apr 07/10 Thody, Graham Campbell Direct Ownership Common Shares 10 - Disposition in the public market -10,000 $0.830
Apr 08/10 Apr 07/10 Low, Kendra Leigh Direct Ownership Common Shares 10 - Disposition in the public market -80,000 $0.800
Apr 08/10 Apr 07/10 Low, Kendra Leigh Direct Ownership Common Shares 51 - Exercise of options 80,000 $0.350
Apr 08/10 Apr 07/10 Low, Kendra Leigh Direct Ownership Options 51 - Exercise of options -80,000
Mar 25/10 Mar 24/10 Glanville, Ross Owen Direct Ownership Common Shares 10 - Disposition in the public market -120,000 $0.750
Mar 25/10 Mar 24/10 Glanville, Ross Owen Direct Ownership Common Shares 51 - Exercise of options 210,000 $0.350
Mar 25/10 Mar 24/10 Glanville, Ross Owen Direct Ownership Options 51 - Exercise of options -210,000 $0.350


Not one but three insiders are telling us that selling BAJ.to at the levels seen in the last few days is a good idea. Do you see a red flag here too, or are you daltonian?

DYODD, dude.

Tuesday, February 2, 2010

Ventana Gold (VEN.to): TD Securities needs to grow a pair


Some analyst dude over at TD Securities named Daniel Earle needs to get a better grip on life. In his latest analysis on Ventana Gold (VEN.to) published yesterday, Earle sticks the title of "We're Not Worried, But Uncertain Timeline Warrants Discount" and then makes his claims.

Now, due to very large and bold-type legal stuff on the report (and I have no idea who you could e-mail to get a PDF copy of this report, oh no no no no) I'm not going to paste any direct words up from the report, but suffice to say that he thinks the risk of Ventana being stripped of its right to acquire Bodega from "bad boy" Gelvez&Co is very low. But until the legal wrangling is done he expects the company to trade at a large discount. Also, he's optimistic that the problem is resolved in 3-6 months. But then later the timeline isn't certain (!) so he's reducing his target to $12 from $15 but maintains his speculative buy recommendation.

Otto says: WHAT THE ****?

Seriously, this is the call of somebody who is crapping himself. As those in the trade would have instantly recognized when checking out the title of Earle's note, when an analyst says 'he's not worried but..." he's leaving a trail of bricks behind as he walks down the street.

We can argue over this-and-that part of the call here, but the basic, bottom line is that IF Ventana gets the land, according to Earle's previous call the company is worth $15. but IF VEN doesn't get the land, the company is worth zero, zip, nada. And therefore, maintaining your argument that the stock is a buy but dropping your target on what is no longer a nuanced situation but a straight binary call is the opinion of a sin-cojones analyst doing a disservice to his company and his clients.

Tuesday, January 26, 2010

Message to Canadian mining analysts covering Colombian gold stocks


This post is for all those analysts in all those Canadian brokerages, shops, houses and newsletters that cover junior goldies in the Norte de Santander department of Colombia, for example Ventana Gold (VEN.to), Greystar Resources (GSL.to), Galway Resources (GWY.v) amongst a lot of others. And really it's more of a question for you guys up there, because I'd really like to know why you refuse to inform your clients about the unstable political situation in that region, why you refuse to pass information on the social upheavals and misery being caused by far-right wing paramilitary terrorists, why you refuse to tell people about the drug trafficking, the mass killings, the attacks on civilian populations, the displacement of entire villages under duress and the underaged girls forced into prostitution.

Why do you stay totally silent about the enormous political risks currently suffered by Norte de Santander? Do you really think that encouraging a bunch of wealthy Canadians to pour money into such an unstable region is a good idea? It seems to me that by not passing on important information about this region you are either ignorant of Norte de Santander and shouldn't be covering the stocks in the first place, or you are deliberately misleading people.

Here follows a translation of this report in Colombia's El Tiempo daily dated to last weekend, featuring the Public Defender Ombudsman Volmar Pérez Ortiz, a man that so good at his job that he was re-elected by Colombia's congress for this important role for a third consecutive term in 2008 (which runs to 2012). This person knows about one thousand times more about Norte de Santander than the equities analysts that pump these stocks to their clients.

Public Defender Ombudsman Warns That Violende Impacts Vulnerable Population

Vólmar Pérez Ortiz says that violence generated by the actions of illegal groups in the Norte De Santander department has a direct impact on the most sensitive sectors.

The National Public Defender Ombudsman also indicated that the cases of violence that communities are exposed to include selective homicides, massacres, forced displacements, threats, attacks and combats using the civilian population as human shields, anti-personnel mines, use and recruitment of children and adolescents to the paramilitry and forced prostitution.

The functionary also said that the illegal groups that operate in the region such as the 'Aguilas Negras' and the 'Rastrojos' have shown a capacity of expanded control over the populations, particularly in the border areas.

"For the Defender of the People Ombudsman, the continued reality of forced transborder displacement in Norte de Santander is worrying , as in other zones of the extensive frontier with Venezuela", said Pérez, who added that the displacements do not have good estimated numbers due to the characteristics of the operations that affect undeclared refugees who do not report their situations to avoid being expelled or as a means of self-protection from the illegal groups.

Vólmar Pérez said that the forced displacements are principally as a consequence of threats and constraints from illegal armed groups on the civilian populations that live in regions close to the border.

Thursday, January 7, 2010

Mo' Ventana (VEN.to): My stars! They finally beginning to notice?


Way back in IKN31 we ran a whole thing on Ventana Gold (VEN.to) and its obvious problem at La Bodega with Los Gelvez. We even extracted the longer note in this blog post dated December 2nd that said:

Here follows an excerpt from the June 14 2008 Technical Report on the La Bodega property:

Surface rights within the property are held by various landowners. The company reports that it has signed exploration access easements with all the surface owners where drilling has been undertaken or planned to be conducted. Additional surface rights may be required to establish a commercial mining operation.

It’s a sure fire certainty that SMLB and/or Gelvez are the major names inside those “various landowners”. What we have here is a serious weakness, a chink in the armour of VEN and its position. VEN might be able to close on the option and secure that very impressive mineralization, but the topsoil (if you like) isn’t included in the deal, and if you’re prohibited from setting foot on the land, it becomes impossible to build a mine and dig the depths. Again, if you want to you can say it’s the leverage point with which SMLB is illegally and immorally blackmailing the poor, hard done by Ventana Gold. It’s just semantics anyway and makes no difference to the facts of the matter.


So today we get a NR from VEN.to that announces the company has secured mineral rights at its property in several place....except (surprise surprise) La Bodega. Here's an excerpt:
"Ventana has two remaining option agreements to complete. The first is for the La Bodega property, which is being disputed by the land owners (see news release dated November 27, 2009, available on the Company's website at www.ventanagold.com). The dispute is an attempt by the land owners to continues here

Oh look....did that say "land owners"? Beginning to see the problem, or do I still need to take a few more crazy pills?

Ventana Gold (VEN.to) looks tired

Welcome to South America, folks! Land of the never-ending legal battle.


Apart from that big dropday when it went to $7.27 or so intraday (then rebounded), today's sub $7.50 is the lowest we've seen Ventana Gold (VEN.to) since its travails began.

So much for the Gelvez crew folding quickly, eh? DYODD.

Monday, December 14, 2009

Friday, December 11, 2009

Ventana Gold (VEN.to): Master Blaster

Eike (for it is he)

Today's insider trades filings on Ventana Gold (VEN.to) are interesting and explain why VEN went through a moment of intraday weakness yesterday that saw the stock under $9. Here's the segment from Canadian Insider:

Ventana Gold Corp. (VEN)

As of December 10th, 2009
Filing Date Transaction Date Insider Name Ownership Type Securities Nature of transaction # or value acquired or disposed of Unit Price
Dec 10/09 Dec 04/09 63X Master Fund Direct Ownership Common Shares 10 - Disposition in the public market -1,000,000 $10.200
Dec 10/09 Oct 15/09 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 2,155,300 $6.021
Dec 10/09 Oct 05/09 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 4,875,300 $5.467
Dec 10/09 Aug 12/09 63X Master Fund Direct Ownership Common Shares 10 - Acquisition in the public market 1,814,200 $4.271
Dec 10/09 Jul 22/09 63X Master Fund Direct Ownership Common Shares 00 - Opening Balance-


The 63X Master Fund is the investment fund run by our pal and Brazilian squillionaire Eike Batista. What we see here is the 8.8m or so shares that Eike bought mostly (8.2m) back in July (and for some reason only registered in August/October) period have finally been filed (and by the looks of things he's not going to sweat over a CAD$1,000 late filing fee, is he?). But we also see that he's dumped a million of the shares in the last few days. The reason for this apparent vote of no confidence must be the legal action that's surfaced between VEN.to and local owners of the 'La Bodega' property, Sociedad Mineral La Bodega (SMLB) and its controllers, the Gelvez family of the Colombian region in question.

Not much doubt that it's a net negative to see Batista selling like this, however much you want to spin it as "wisely taking profits, still owns plenty" to feed some illusion or other. BUT, one thing that does strike me is that all of a suddenly sudden, Batista (via his 63X Master Fund) is suddenly keen on being transparent about his trades when previously he didn't give a damn about filing his inside position correctly. One guess here....and it is a pure guess...is that Eike wants to get a few nerves flowing through the marketplace about VEN.to stock. He'd actually like to see the price drop. If that's so, as he currently owns 7.8m or so VEN shares he's either shooting himself in the foot (virtually impossible) or he's looking to add at a lower price later.

OK, this could go down as an extrapolated conspiracy theory and Occam and his razor may well disagree with me here. Another thing to note is that the 1m share sale puts Eike under 10% owned and no longer an insider of record (i.e. he can do what he wants out of the public gaze) But Eike isn't one of the world's most successful investors by sheer chance, y'knowz.

So the bottom line is that this story has a long way to travel yet, but Eike has added a very short term negative to the mix with his sale. DYODD.

Wednesday, December 2, 2009

Ventana Gold (VEN.to): We extract

Just time for another quickie before going to do other things, because by the looks of the mailbox there's a lot of interest in Ventana Gold (VEN.to). So here's a small extract from the article on VEN in IKN31 published last Sunday. I'm not going to give away the much of the text offered up to subscribers, but it's fair enough to give a lead and point them as to where DD is worthwhile.


Here follows an excerpt from the June 14 2008 Technical Report on the La Bodega property:

Surface rights within the property are held by various landowners. The company reports that it has signed exploration access easements with all the surface owners where drilling has been undertaken or planned to be conducted. Additional surface rights may be required to establish a commercial mining operation.

It’s a sure fire certainty that SMLB and/or Gelvez are the major names inside those “various landowners”. What we have here is a serious weakness, a chink in the armour of VEN and its position. VEN might be able to close on the option and secure that very impressive mienralization, but the topsoil (if you like) isn’t included in the deal, and if you’re prohibited from setting foot on the land, it becomes impossible to build a mine and dig the depths. Again, if you want to you can say it’s the leverage point with which SMLB is illegally and immorally blackmailing the poor, hard done by Ventana Gold. It’s just semantics anyway and makes no difference to the facts of the matter.


Disclosure: No position in VEN.to. Not long and not short. Best advice is 'avoid'. DYODD, dude.


PS: Semi OT- Congrats to PEZ for securing its land rights; overdue but welcome.

Friday, November 27, 2009

Ventana Gold (VEN.to): Oh Noes!!! Canadian Analysts Now Forced to Examine Colombia Political Risk Shock Horror

The most used phrase in many Canadian brokerages this morning is "Jeesh...what does this line mean? Hey, anyone speak Spanish round here?" as Ventana Gold (VEN.to), hotpot mining story of the year, announced after the bell yesterday that;

VANCOUVER, BRITISH COLUMBIA--(Marketwire - 11/26/09) - Ventana Gold Corp. (TSX:VEN - News) ("Ventana" or "the Company") has been advised that Sociedad Minera La Bodega Limitada (or the "Vendor"), the owner of the mineral rights to the La Bodega property in Colombia, is seeking an arbitration in relation to an option agreement (the "Option Agreement") with CVS Explorations Ltda. ("CVS"), Ventana's 100%-owned subsidiary. The Option Agreement provides for CVS to acquire the La Bodega property mineral rights through a series of staged payments as detailed below.

The request for arbitration is an attempt by the Vendor to invalidate the Option Agreement and have the property returned to the Vendor. CVS has operated under the Option Agreement for almost four years without any performance default or allegation of default. The Vendor's request for arbitration is based on arguments that the Option Agreement fails to comply with yada yada continues here

Well guess what, folks? After all my warnings about the total lack of attention paid by Canadian investment houses to the significant risk in that region of Colombia, I'm just going to get our friend the owl to comment on this development:

There'll be details and background in IKN31, out Sunday. In the meantime, here's a hint for all you guys playing catchup on the DD; check how many times the name "Gelvez" comes up in local political and administrative circles in the California/Santander region.